Trading platform & site functionality
Hubai.uk positions itself as an advisory gateway for businesses and professionals who want to apply decision intelligence. The pitch is straightforward: tell the tool your role, company size, objectives, and budget, and you will receive an explainable AI stack, a recommended rollout order, risk checks, and a transparent ROI scenario. That description sounds more like a guided advisory or consulting wizard than a download-and-install product. The value proposition is plausible in today’s market, where organizations want structured, vendor-agnostic blueprints for adoption. What remains unclear from the materials we could access is whether the outputs are tailored by human analysts or generated from templates.
Technically, the domain sits behind a mainstream content delivery and security layer, and our requests encountered a challenge script before loading certain assets. This is not unusual; many operators deploy security challenges to filter bots and preserve resources, but it does mean some visitors will initially see less content. The site presents as English-language with a UK country-code domain, which can help with local trust when the operator is indeed UK-based. That said, a UK domain alone does not confirm a UK-registered company, and the WHOIS information we saw did not reveal an owner. Prospective clients should not equate polished presentation or a security gateway with business credibility—these are separate concerns.
From what we could observe, the branding and copy emphasize transparency of the proposed stack and ROI, which is a sensible promise in this category. However, we did not see clear, easy-to-find links to a company imprint, legal entity name, or terms of service in the limited content available to us. It is possible those documents exist behind navigation steps or forms, but they were not obvious during our snapshot review. Before engaging, you should expect to see a privacy policy, terms of service, refund or cancellation terms, and a physical or registered address. If the site intends to service businesses, it should also provide a company registration reference and, if relevant, VAT details.
The core deliverable—an “explainable AI stack” with risk checks and ROI scenarios—should be supported with actual assumptions, data sources, and sensitivity analysis. For example, a credible ROI model spells out adoption costs, integration complexity, training load, expected productivity uplift, and error rates under different scenarios. A meaningful rollout plan cites change management, governance, and internal control touch points rather than just listing tool names. Without these details, the output risks being generic guidance that anyone could assemble from public articles. If you test the service, ask for a sample anonymized output, or request case studies with named client references you can contact independently.
License & regulatory status
An AI advisory site does not typically need a financial license, and we saw no overt claims of being authorized by a financial regulator. However, if the operator were to offer investment advice, portfolio recommendations, or regulated credit-broking activity, UK rules would trigger authorization requirements with the FCA. We did not see any FCA reference numbers or claims to such authorization in the limited materials we could access, and we are not suggesting this site offers those services. The point is narrower: if a vendor’s claims stray into regulated territory, they must hold the relevant permissions. Where there is no such activity, this is not applicable.
Data handling is more squarely relevant. If hubai.uk collects business details, contact information, or other personal data from UK or EU users, the operator must comply with the UK GDPR and Data Protection Act 2018. That includes having a clear privacy notice, a lawful basis for processing, data retention policies, and, where appropriate, registration with the UK Information Commissioner’s Office (ICO). We could not independently verify the site’s privacy documentation or any ICO registration; it was not visible in our limited snapshot. Users should look for a visible privacy policy and cookie disclosures, and ask for a Data Processing Agreement if they plan to share sensitive data.
Marketing and performance claims also have rules. In the UK, the Advertising Standards Authority (ASA) expects marketers to substantiate objective claims—particularly ROI figures—under the CAP Code. Promises of “transparent ROI scenarios” should therefore be backed by reasonable, reproducible assumptions, not just optimistic benchmarks. If a vendor offers headline savings without clear assumptions, or hides caveats in inaccessible materials, that is a red flag. We did not observe detailed substantiation in our snapshot, which reinforces the need to ask for methodology before you take any figures to your leadership team.
Finally, corporate identity matters for enforceability. As a rule of thumb, UK-facing websites should display a legal entity name and registered address in their footer or legal pages, and ideally a Companies House number to avoid ambiguity. The WHOIS record we saw did not disclose the owner, and the public-facing materials we could reach did not clarify the operating entity. We are not saying this information does not exist, only that it was not apparent during our review. If you cannot determine who you would be contracting with, you lack a critical line of accountability if deliverables are delayed, deficient, or disputed.
User feedback
Given the domain’s February 2026 registration, it is not surprising that there is little visible, third-party feedback. Our reputation checks did not surface credible independent reviews or detailed case studies tied to verifiable client identities. The absence of public complaints can be good news, but in a young site’s case it more likely reflects limited exposure. New brands often have a runway before organic feedback arrives—good or bad. This timing gap is precisely why extra caution is prudent in the early months of any online service.
In this particular niche—AI roadmapping and decision support—complaints we see elsewhere cluster around a few themes. Clients pay for a discovery workshop and receive what feels like a lightly customized template rather than a deeply contextual plan. Others report upsells to managed implementation with vague milestones, followed by missed timelines and difficulty obtaining refunds. We are not attributing these problems to hubai.uk, only highlighting patterns that recur in the category. A robust vendor will anticipate these concerns and proactively share references, named consultants, and milestone-based statements of work.
Because verified feedback is thin, prospective buyers should stage their engagement. Ask for a sample anonymized deliverable, then request two references you can speak with directly, not just written testimonials. If the vendor declines, insists on full upfront payment, or pushes an unusually aggressive discount that expires within hours, consider it a pressure tactic rather than a client-first posture. Above all, keep communication in writing and avoid phone-only commitments; a clear paper trail can make the difference if you later need to contest charges or negotiate remediation.
Deposits & withdrawals
We did not see published details about accepted payment methods, refund windows, or cancellation rights during our limited review. In this space, vendors commonly accept credit cards, bank transfers, or invoices for business clients. As a risk-control measure, prefer a credit card over a wire for initial, low-value engagements; card schemes offer chargeback avenues if the service is not delivered as described. Avoid cryptocurrency or irreversible methods, which provide you no practical recourse if the relationship goes sideways. If the vendor proposes an unusually large upfront payment, ask to split it into milestones tied to concrete deliverables.
Refund friction in consulting often stems from ambiguous scopes. Contracts may label discovery fees as non-refundable, even if the output falls short of expectations. To protect yourself, insist on a written statement of work that defines acceptance criteria, timelines, and what happens if scheduling slips. If you are a consumer rather than a business, UK distance-selling rules can sometimes provide cooling-off rights, but most B2B engagements fall outside those protections. When in doubt, obtain a written refund and cancellation clause that references jurisdiction and dispute resolution.
If payments are routed through a third-party processor, screenshot the checkout page and save all emails and invoices. These records will be vital if you need to open a dispute with your bank or the processor. For larger, multi-month projects, consider using escrow or staggered invoicing that unlocks upon acceptance of each phase. Reputable firms rarely refuse this structure; resistance indicates either cash-flow stress or an intent to front-load revenue before delivery, neither of which bodes well for client outcomes.
Why unregulated brokers are risky
Because advisory services like this are not typically overseen by financial regulators, you do not receive protections comparable to those offered by, for example, the FCA for authorized investment firms. If a dispute occurs, your remedies are contractual and civil in nature, not backed by a compensation scheme. Young, lightly documented websites also carry continuity risks: operators can rebrand, relocate hosting, or simply shutter the site. With a CDN layer in front, tracing ultimate infrastructure provides little comfort about real-world accountability. Your best protection is to identify the legal entity, verify its registration, and contract on your terms.
There is also a data risk unique to technology advisory. To tailor recommendations, you may be asked for sensitive operational metrics, budgets, or pipeline data. Without a robust privacy policy, a signed non-disclosure agreement, and a clear data-processing arrangement, you risk exposing confidential business information with no realistic clawback if it is misused. Ask where data is stored, who has access, and how long it is retained. If the vendor cannot answer plainly, do not share sensitive inputs.
Finally, consider conflict-of-interest risk. Some advisory shops earn affiliate fees or kickbacks for steering clients to specific tools while still claiming vendor neutrality. That can quietly bias their “ROI scenarios” toward partners rather than your true needs. Ask the operator to disclose all financial relationships with recommended vendors and to attest in writing that no compensation will be received for product placements unless explicitly disclosed. Transparency here separates genuine advisors from marketing funnels.
How to get help if you’ve been scammed
If you have already paid and suspect the service is not as described, act quickly. Contact your card issuer or bank and explain that you believe you were misled or did not receive the contracted deliverables; ask whether a chargeback or dispute can be initiated under “services not provided” or “not as described.” Gather evidence now: emails, invoices, chat logs, and any representations made on the site. If you paid by bank transfer, ask your bank about an immediate recall, though success depends on timing and the recipient’s bank. Avoid sending additional funds to “unlock” support or expedited refunds—this is a hallmark of advance-fee tactics.
File formal reports to create a documented timeline. In the UK, report to Action Fraud and keep the reference number. In the United States, use the FBI’s IC3; in other jurisdictions, contact your national cybercrime or consumer protection authority. If the operator provided what looks like regulated investment advice, notify the FCA; if advertising claims seemed misleading, consider a complaint to the ASA. For suspected misuse of your personal data, lodge a complaint with the ICO or your local data protection authority.
For hands-on guidance pulling your case together, you can contact our team at reportscammedfunds.pro. We can help you structure your documentation, assess viable recovery avenues, and avoid common pitfalls such as falling victim to recovery scams that promise guaranteed outcomes for upfront fees. Reach out even if you are unsure; a quick triage can clarify next steps and help you decide whether to escalate or proceed with a structured negotiation. Time matters in transaction disputes, so do not delay.
Conclusion
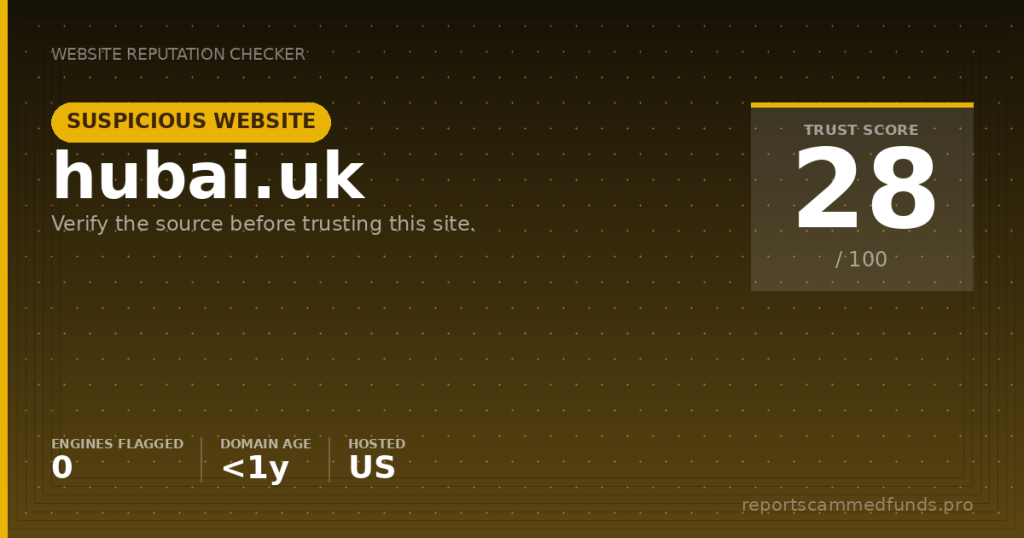
Hubai.uk arrives with a contemporary pitch and some technically competent hosting choices, but there is not enough public-facing detail to award unqualified trust. The domain is new, the operator’s identity is not disclosed in registry data, and we could not independently verify core commercial terms from the materials we could access. None of these facts prove malicious intent, yet collectively they limit your ability to assess risk and enforce accountability.
If you are considering engagement, create a short checklist: identify the legal entity and registered address, ask for a Companies House number if UK-based, request two client references you can call, and obtain a clear statement of work with refund and cancellation terms. Confirm the privacy policy and any data-processing commitments before you share sensitive inputs. Where possible, start with a low-stakes, milestone-based payment structure via a reversible method such as a credit card.
Our verdict is cautious: we classify hubai.uk as a Suspicious Website due to its youth and sparse disclosures, though we did not find evidence of malware or overt phishing. This is not a final judgment on the operator’s intentions, only a practical risk rating for readers deciding whether to engage. Proceed only after independent verification, and do not compromise on identity checks, written terms, and payment protections.